

Navy Federal Credit Union

- 43.19K Reviews
- 3.7
- Downloads
- 10,000,000+
Our take on Navy Federal Credit Union from Appgk
Choosing a mobile banking app is less about finding the flashiest interface and more about knowing whether it will make ordinary money tasks easier. Navy Federal Credit Union is the finance app from Navy Federal, and I found its appeal fairly clear: it puts credit-union account management in a phone-based format without charging for the app itself. The developer is Navy Federal, the app is free, and its audience is broad enough to carry an Everyone content rating.
I would recommend it first to people who already use Navy Federal and want a practical way to check their finances away from a computer. It can also suit someone joining the credit union who prefers handling routine banking from a phone. I would not choose it simply because the name sounds familiar, though. The useful question is whether you want a dedicated Navy Federal experience rather than a general money-management tool that combines accounts from several institutions.
What to expect from the Navy Federal mobile experience
Navy Federal Credit Union is a finance app rather than a budgeting game, investment dashboard, or independent wallet. That distinction matters because its value depends on your relationship with Navy Federal. If your accounts are there, the app is meant to become the place you check balances, review activity, and begin everyday account tasks. If your financial life is spread across several banks, you may still need another app for the wider picture.
The app has been available since July 29, 2011, so it is not a brand-new experiment. Its current version is 2026.8.1, and it requires iOS or Android 11 or later. That operating-system requirement is worth checking before installing, especially if you keep an older phone for banking. A compatible device is part of a smooth first session; discovering the requirement after clearing space and preparing to sign in is an avoidable annoyance.
Best Parts of Navy Federal Credit Union
Things to Keep in Mind About Navy Federal Credit Union
Its public reception is mixed but substantial: the app carries a 3.7 average from around 110 thousand ratings, with roughly 43 thousand written reviews. It has also passed the ten-million-install mark. I read those figures as evidence of a large, established user base rather than a guarantee that every person will enjoy the interface. A finance app can work perfectly for one member and feel awkward to another depending on account setup, phone habits, and the tasks they perform most often.
The phrase associated with the app is “Our Members Are the Mission,” but I paid more attention to the practical experience than to the slogan. The strongest reason to keep it installed is convenience: a quick route to your Navy Federal relationship when you are away from a branch or desktop browser. The weaker reason would be expecting it to replace every financial tool you use.
News and Features Related to Navy Federal Credit Union

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Who gets the most from it
I see the best fit in a member who wants a reliable daily check-in. For example, imagine buying groceries after work and wondering whether a recent payment has cleared. Opening the app, checking the relevant account activity, and confirming the available balance is much more useful than waiting until you reach a laptop. That small moment is the kind of success a banking app should deliver quickly.
It is also a sensible companion for people who travel, move between locations, or simply dislike organizing paperwork. A phone gives you a more immediate view of account activity, which can help you notice an unfamiliar transaction sooner than you might during a weekly desktop session. I would still treat the app as one part of responsible account monitoring, not as a substitute for reviewing statements carefully.
Don't want to read the full review?
On the other hand, I would hesitate to recommend it to someone who wants a single neutral dashboard for checking, savings, cards, loans, investments, and accounts held elsewhere. The Navy Federal connection is the point, and that focus is a limitation if you want broad aggregation. A general personal-finance app may be better for comparing your entire financial life in one place, while this app is more appropriate for managing the Navy Federal side directly.
Setting it up without making the first session stressful
Before installing, I would confirm that the phone runs at least Android or iOS 11. I would also make sure I know which Navy Federal sign-in details I normally use and that I can receive any account-security prompts required during access. I would not begin the process in a rushed checkout line or on an unreliable connection. Banking setup is easier when you can read each screen and stop if something looks unfamiliar.
Screenshots
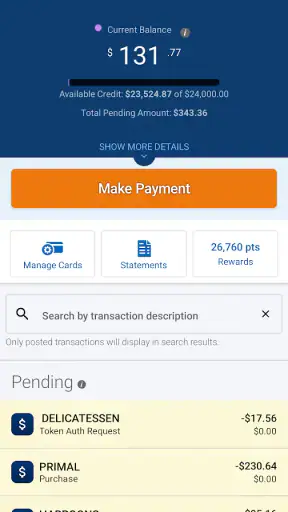
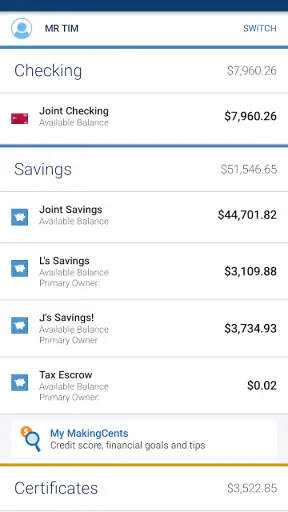
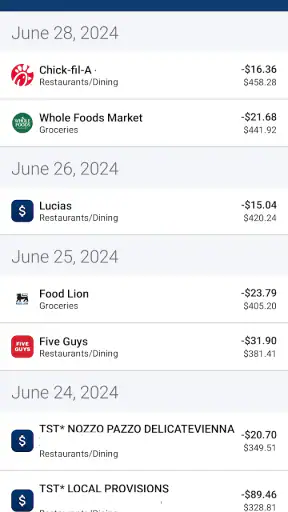
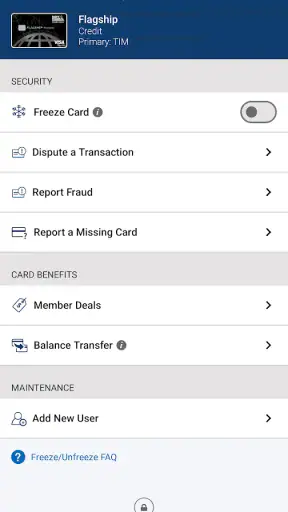
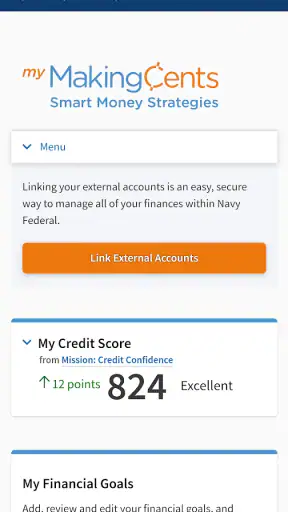
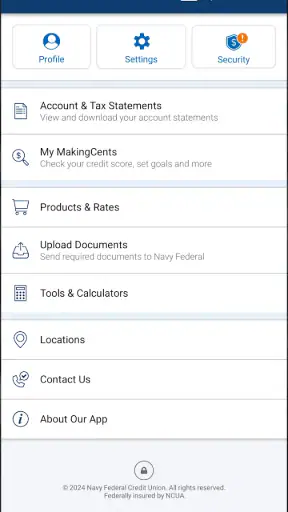
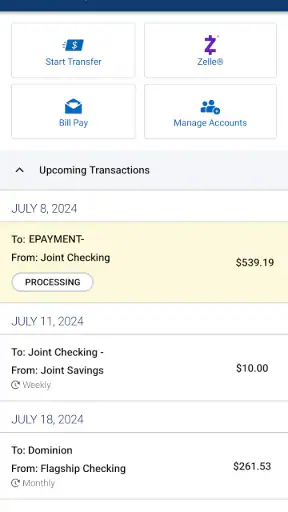
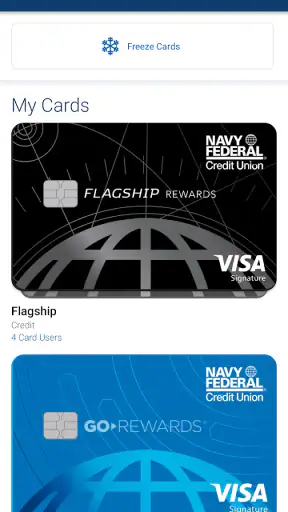
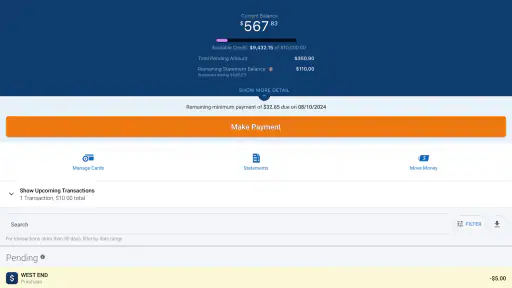
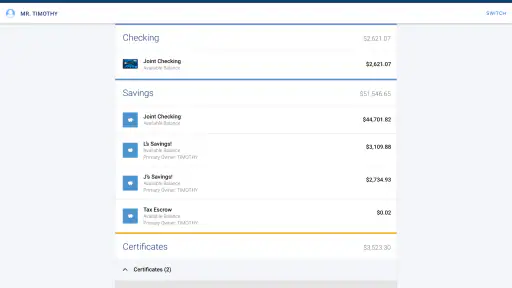
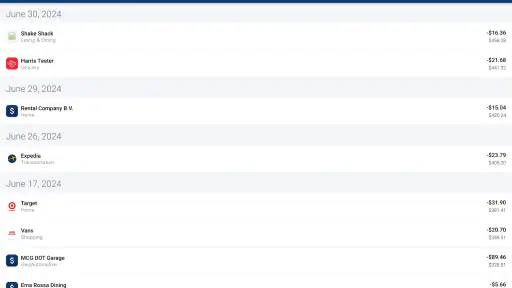
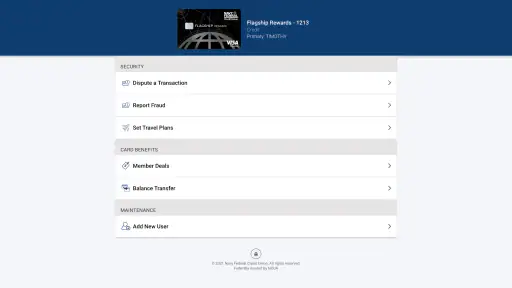
After installation, the first meaningful goal should be modest: reach your account view and recognize the information shown there. Do not try to explore every menu immediately. I recommend signing in, checking that the displayed accounts are the ones you expect, and then reviewing recent activity. This creates a useful baseline. If an account, balance, or transaction looks wrong, you can investigate before attempting a more consequential action.
One practical habit is to decide in advance what “success” means for your first session. For a new member, it may be confirming that access works and identifying where the main account information appears. For an existing member moving from a browser, it may be finding the same routine task you perform most often. A narrow first objective prevents the common mistake of judging the whole app after getting lost in an unfamiliar navigation path.
I would also avoid treating the installation itself as proof that everything is ready. The app is free, but the financial relationship behind it is separate from the download. In other words, installing a free finance app does not automatically turn it into a universal banking service. Your ability to use it meaningfully depends on having the appropriate Navy Federal access and accounts.
Your first successful action
For me, the best first action is a simple activity check. Once signed in, look at the latest transactions and compare them with something you genuinely remember doing. A recent purchase, transfer, or deposit can serve as an anchor. This is more reassuring than merely seeing a welcome screen because it confirms that you are looking at the right account information and can interpret the activity list.
After that, try the one task that motivated you to install the app. If you wanted mobile visibility, stop after confirming the balance and recent activity. If you wanted to handle a routine payment or account action, take your time reading the review screen before confirming anything. I prefer this staged approach because it separates access from action: first prove that you can see the right information, then decide whether you are ready to change anything.
A useful workflow is to use the app for observation before using it for decisions. Check an account, identify a transaction, and note how the information is organized. On a later visit, you will spend less time searching and more time completing the task that brought you there. This is especially helpful for first-time users who feel pressure to understand every banking option at once.
There is another small but important trade-off here. Mobile access is convenient precisely because it is close at hand, but that convenience can encourage rushed confirmations. I would not approve a financial action while distracted, and I would pause whenever a destination, amount, or account label is unclear. The app can shorten the path to a task; it cannot make a careless review safe.
Where new users may hesitate
The first point of confusion is usually not installation but context. A user may expect a general-purpose finance app and then realize that the experience is centered on Navy Federal. That is not a flaw in itself, but it changes how you should evaluate it. Think of it as a mobile front door to your Navy Federal relationship, not as a replacement for every financial service you use.
Another possible friction point is deciding whether a problem belongs to the app or to the underlying account. If you cannot see expected information, do not immediately assume the interface is broken. Check that you used the intended sign-in route, that you are viewing the correct account area, and that the information you expect should be available through your Navy Federal relationship. When the issue concerns account access rather than navigation, contacting Navy Federal through its official support channels is more sensible than repeatedly reinstalling the app.
Users can also misread a visible balance as a complete picture of their finances. A balance is useful, but recent activity, pending items, and the timing of transactions can affect how much money is truly available for a decision. I recommend reviewing the surrounding activity instead of relying on one prominent number. This is one of the less obvious habits that makes mobile banking safer: use the app to verify context, not just to glance at a headline figure.
Notifications and phone security deserve attention too, even though they are easy to overlook during setup. I would keep the device itself protected, avoid sharing access casually, and sign out or lock the phone when appropriate. The app’s Everyone rating describes its content suitability, not a promise that every phone environment is secure. Your device habits remain part of the banking experience.
How it compares with usual alternatives
Compared with visiting a branch, the app is faster for a balance check or transaction review and available when you are already carrying your phone. The trade-off is that a branch can be more comfortable when you need guided help with a complicated account question. I would use the app for routine visibility and choose personal assistance when the issue requires explanation, verification, or a broader conversation.
Compared with a desktop banking site, a mobile app is better suited to short sessions. You can check something immediately instead of waiting to sit down at a computer. A desktop browser may still feel better for careful document review, extended planning, or users who dislike navigating financial screens on a small display. I would keep both options in mind rather than forcing every task into the phone.
Compared with an independent budgeting app, Navy Federal’s app has a narrower purpose. A budgeting tool may help categorize spending across multiple institutions, while this app keeps the focus on Navy Federal access and activity. Neither approach is automatically superior. If your main question is “What is happening in my Navy Federal account right now?” this app is the more direct choice. If your question is “How does all my spending fit together?” a broader tool may offer better perspective.
That comparison also explains why I would not judge the app only by its rating. A 3.7 average suggests there is room for interface friction or inconsistent experiences, but ratings rarely reveal whether the reviewer wanted a credit-union portal, a full budgeting suite, or something else entirely. I would weigh the app against your actual workflow: frequent Navy Federal member, occasional browser user, or multi-bank planner.
What to do after the first visit
Once the first login and activity check feel comfortable, build a small routine around the app instead of opening it without a purpose. I would use it after important account activity, before a larger purchase, and whenever I need to confirm whether something has posted. The goal is not constant checking; it is creating a dependable moment of verification before money decisions.
A second useful step is to identify the screens you return to most. Remember the path to account activity and the location of the action you installed the app to perform. You do not need to memorize every option. Familiarity with two or three important routes will make the app feel much less demanding than trying to learn the entire interface in one sitting.
If you manage more than one Navy Federal account, slow down when switching between them. Read the account name and relevant details before beginning an action. This is a simple safeguard, but it is particularly valuable on a phone where several accounts may appear in a compact layout. I would rather spend a few extra seconds confirming the destination than rely on memory.
For someone deciding whether to keep it, my test is straightforward: after a week or two, ask whether the app has reduced the effort required for your normal Navy Federal tasks. If yes, its free price and established availability make it an easy app to retain. If you still prefer the desktop site for everything and rarely need mobile access, uninstalling it may be reasonable. A finance app should earn its place through useful habits, not because it happens to be installed.
Overall, I see Navy Federal Credit Union as a focused mobile banking companion with a clear audience. It is not the right answer for a person seeking a complete cross-bank financial command center, and the middling average rating suggests that the experience will not be perfect for everyone. Still, for a Navy Federal member who wants quick account visibility and a practical path to everyday banking from a compatible phone, it is worth trying. Start with one calm login, verify a familiar transaction, and let that first successful action decide whether it fits your routine.
Navy Federal Credit Union FAQ
What is Navy Federal Credit Union, and who can join?
Navy Federal Credit Union is a member-owned financial institution offering checking and savings accounts, credit cards, loans, mortgages, and other financial services. Membership is generally available to active-duty military members, veterans, Department of Defense personnel, certain government employees, and eligible family members. Before downloading the app, confirm that you meet the current membership requirements through Navy Federal’s official website.
What can I do with the Navy Federal mobile app?
The Navy Federal mobile app lets eligible members manage many everyday banking tasks from an Android or iOS device. You can typically check balances, review transactions, transfer funds, pay bills, deposit checks using mobile check deposit, locate branches or ATMs, manage cards, and apply for selected products. Available features may vary by account type, device, location, and app version.
Is the Navy Federal app safe to use for mobile banking?
The app is designed with security features intended to protect your account and personal information, such as encrypted connections, secure login options, device authentication, alerts, and card controls. However, no banking app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your device updated, avoid public Wi-Fi for sensitive activity, and never share verification codes or login details.
Does Navy Federal charge fees for using its mobile app?
Navy Federal generally does not charge a separate fee simply for downloading or using its official mobile banking app, although normal account terms and service conditions still apply. For example, fees could relate to specific transactions, overdrafts, transfers, wire services, or other banking products. Mobile data charges from your carrier may also apply, so review the current fee schedule before using particular features.
What should I do if the Navy Federal app is not working or I cannot log in?
If the app fails to open, freezes, or rejects your login, first check your internet connection and confirm that you are using the latest version from the official app store. Restarting the app or device may help, but avoid repeatedly guessing passwords. Use Navy Federal’s official support channels for account access problems, and contact the credit union immediately if you notice suspicious activity or an unauthorized transaction.











